Zero-depreciation — "zero-dep" or "nil-dep" — is the most useful (and most mis-sold) add-on in motor insurance. Here is what it actually changes, with numbers you can check against your own policy.
Depreciation, in one minute
Your car loses value every year, and at a claim the insurer deducts that depreciation from the parts it replaces:
- Plastic, rubber, fibre parts (bumpers, clips, seals): ~50% deducted
- Tyres and tubes: 30–50% depending on age
- Metal parts: 0% in year one, rising to 30–40% by year five
- Glass: no depreciation
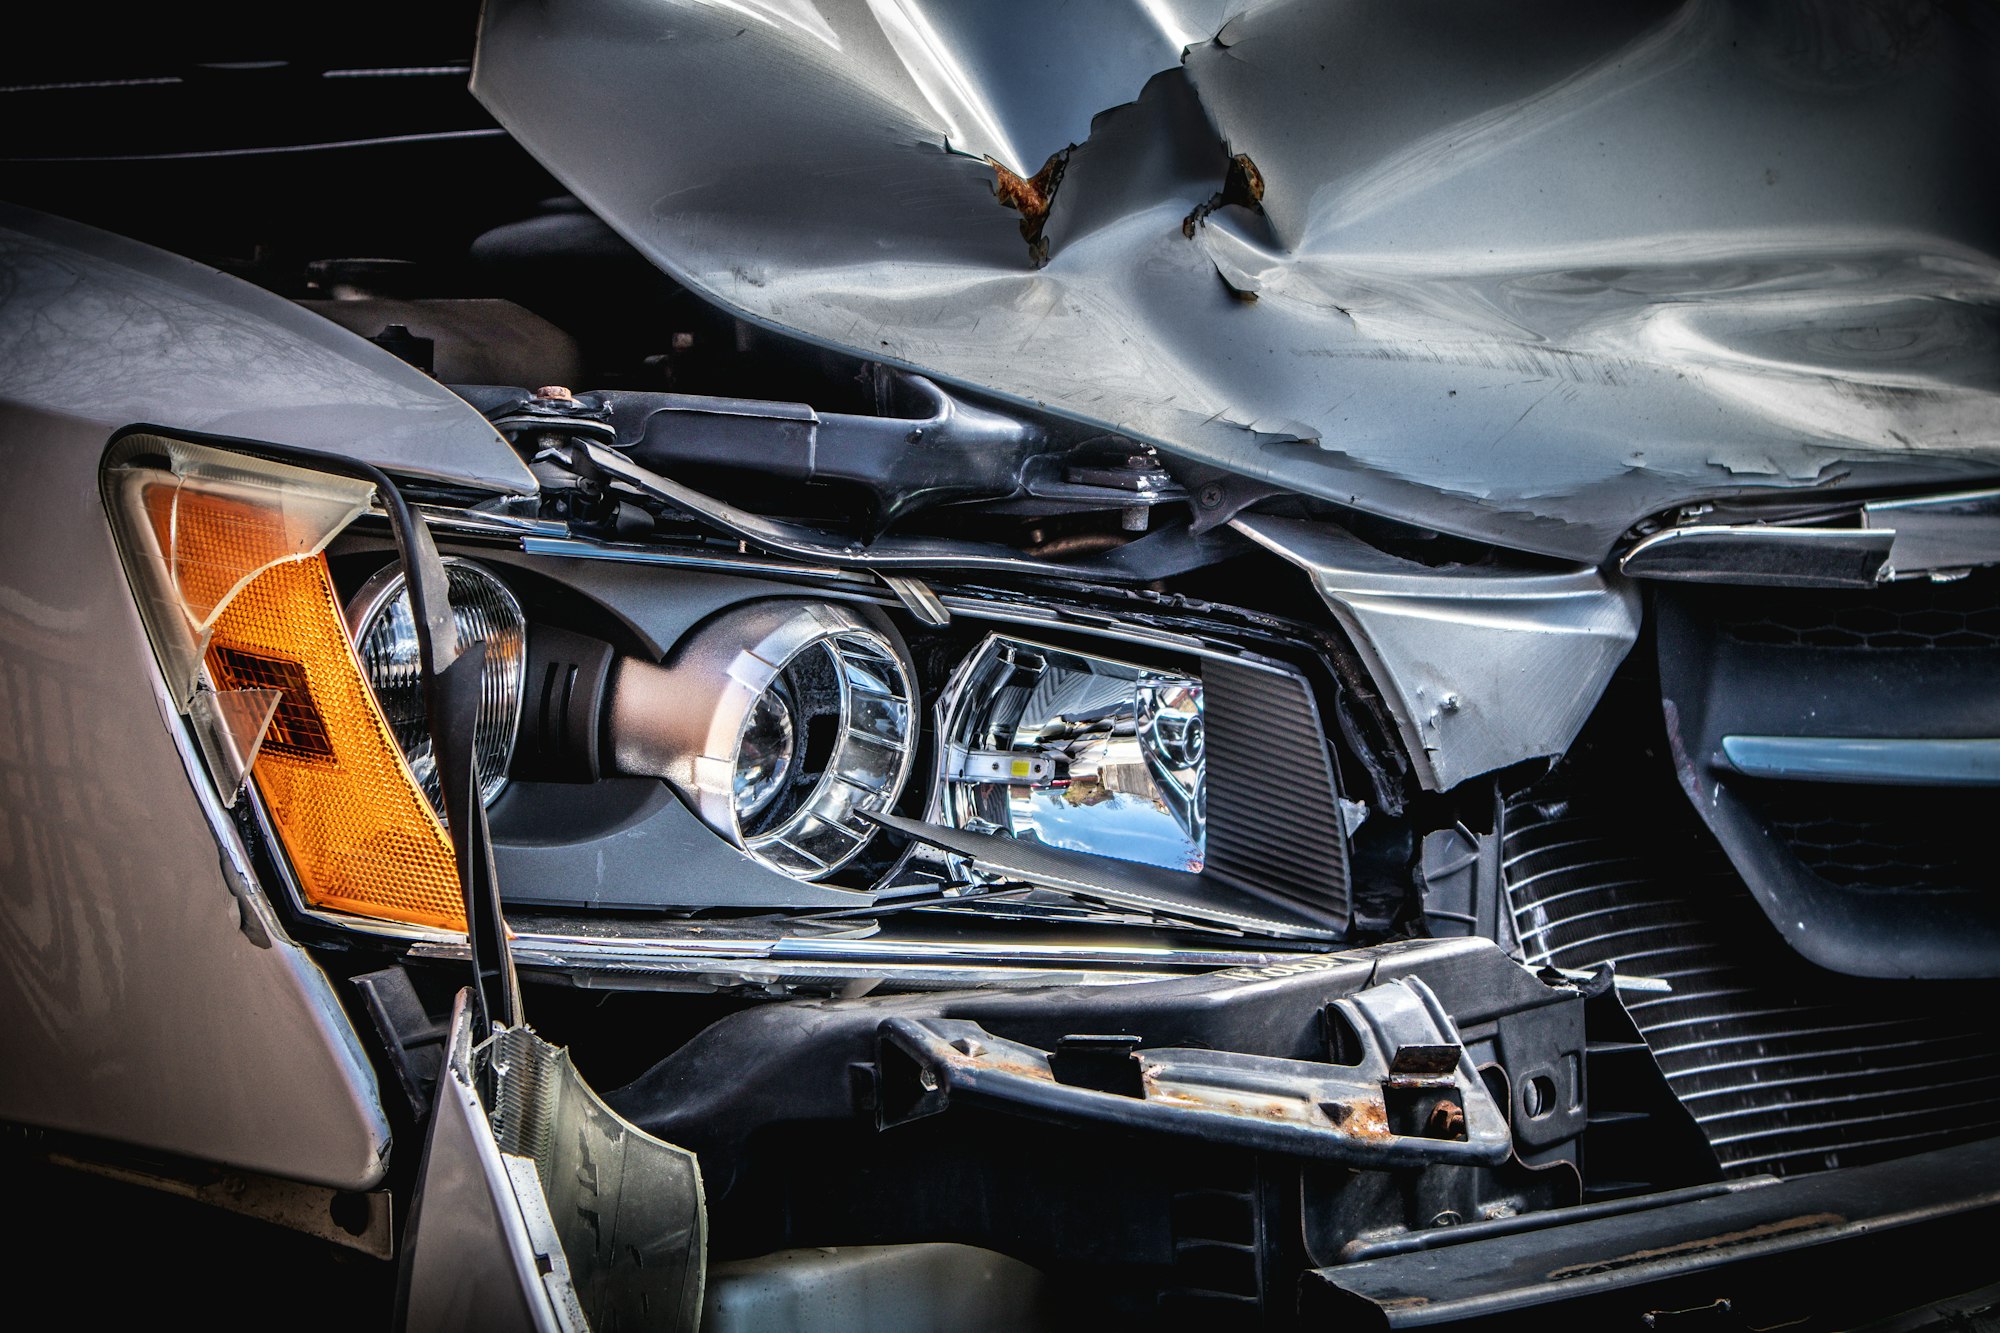
On a ₹40,000 repair bill after a frontal knock — bumper, headlamp, bonnet edge, one tyre — standard comprehensive cover might pay ₹28,000–₹31,000 after these deductions. You fund the rest.
What zero-dep changes
With the zero-depreciation add-on, the insurer waives the depreciation on replaced parts and settles the full (claimed, invoiced) cost, subject to the policy's terms. The same ₹40,000 repair settles close to ₹40,000 — you pay only standard deductibles and any non-covered items like consumables, unless you also add those covers.
What it costs
Typically 15–25% more than comprehensive-only premium for cars up to five years old. For a family hatchback that is often ₹2,000–₹4,000 a year — usually recoverable in a single avoided out-of-pocket repair.
The fine print to actually read
- Age limits — most insurers offer zero-dep only up to 5 (sometimes 7) years of vehicle age.
- Claim count limits — many policies cap the number of zero-dep claims per year (commonly two).
- Excluded parts — some insurers still apply depreciation to tyres and tubes unless you add a separate cover.
When we say skip it
- Very old cars (8+ years) where the add-on may not be available or the premium stops making sense.
- Low-value, high-age vehicles where parts are cheap and the depreciation deduction is small in rupee terms.
When we say take it
New cars, cars on finance, and anything driven daily in Coimbatore traffic — yes. One scrape against a compound wall pays for years of the add-on.
At renewal, we compare zero-dep terms across insurers — the limits and exclusions differ more than the premiums do. Send us your current policy through the contact page and we'll show you the difference line by line.